
Calm Returns, Where to Watch
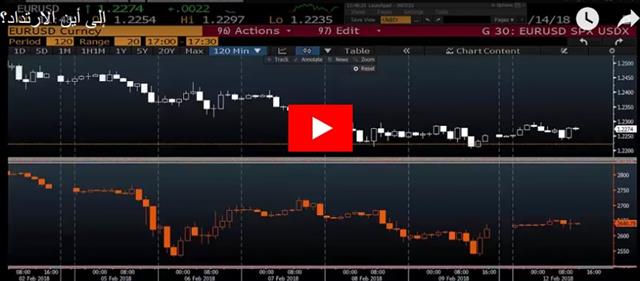
Just as bloogers and analysts began writing about Monday's sharp market rebound, indices around the world are back in the red, yet off their lows. One relationship that's increasingly taking hold is the inverse relation between indices and the US dollar. Interestingly, USD remained weak despite the overnight sell-off in Tokyo and early Europe. JPY, EUR and CHF are the strongest, while GBP backs off its highs following stronger than expected inflation data. 120 pip gain was locked in the EURUSD trade.
إلى أين الارتداد؟ (فيديو للمشتركين)
One clue on whether Monday's bounce will last was in the announcement of a White House infrastructure plan. It surely faces a tough test in Congress but it highlights the administrations priorities; or more aptly, the lack of an emphasis on deficit reduction.
It came along with fresh White House projections which are undoubtedly optimistic and still foresee a nearly $1 trillion deficit next year. With the potential for more stimulus in the pipeline and continued high military spending, the bond market is beginning to worry about debt issuance.
US 10-year yields ticked another basis point higher Monday to 2.86% and as high as 2.89%. There is a sudden focus on borrowing levels and it seems almost inevitably that some type of shudder – small or large – will hit stocks once 3% is breached.
A pair of big drivers towards or away from that level is likely on Wednesday with US CPI and retail sales data.
Latest IMTs
-
My English Webinar at 1pm London
by Ashraf Laidi | Oct 19, 2026 9:31
-
Gold Hourly & Daily
by Ashraf Laidi | Oct 16, 2026 13:59
-
Gold vs Silver & the Ratio
by Ashraf Laidi | Oct 15, 2026 13:02
-
Live on Instagram in 30 mins
by Ashraf Laidi | Oct 14, 2026 11:35
-
ندوتي مساء الثلاثاء مع ضمان ماركتس
by Ashraf Laidi | Oct 12, 2026 16:11